From pre-approval to keys in hand.
Start My Home SearchBuying a home is a big decision, and I want you to make it with real information. I've spent more than 12 years in Arizona real estate, and as a third-generation Phoenix native, I know how the Valley's areas, commutes and price points compare. I'll help you set a realistic budget, show you what it buys in each part of the Valley, and negotiate for you from the first offer to closing. Relocating from out of state? I've helped buyers purchase remotely, with video and FaceTime walkthroughs before they ever set foot in Arizona.
No surprises. Here's exactly what happens between "I'm thinking about buying" and "these are my keys." Tap any step below to learn more.
Every region below has its own price point, school options, and commute profile. Pick a starting point and I'll walk you through what's realistic there.
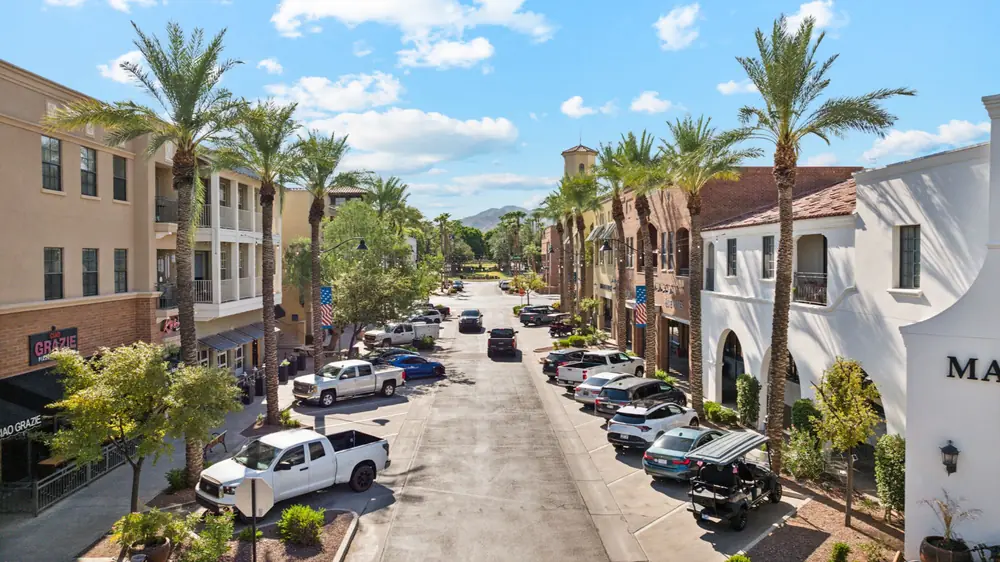 8 communitiesWest ValleyBest value for new construction: Buckeye, Goodyear, Surprise & WaddellExplore West Valley
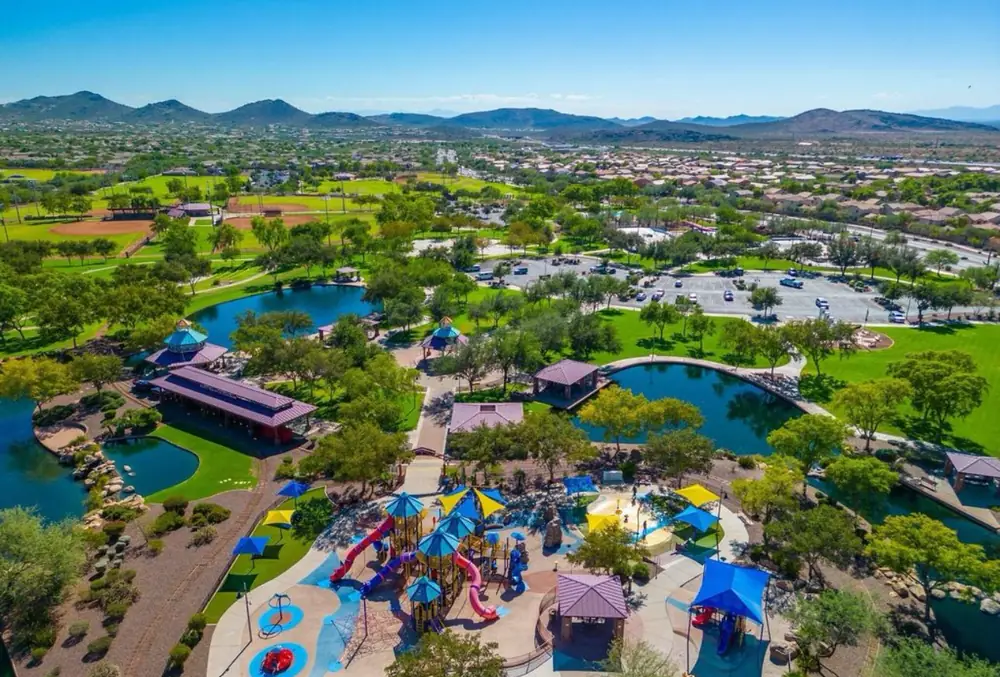 6 communitiesNorth ValleyNewer builds and master-planned living in North Phoenix & AnthemExplore North Valley
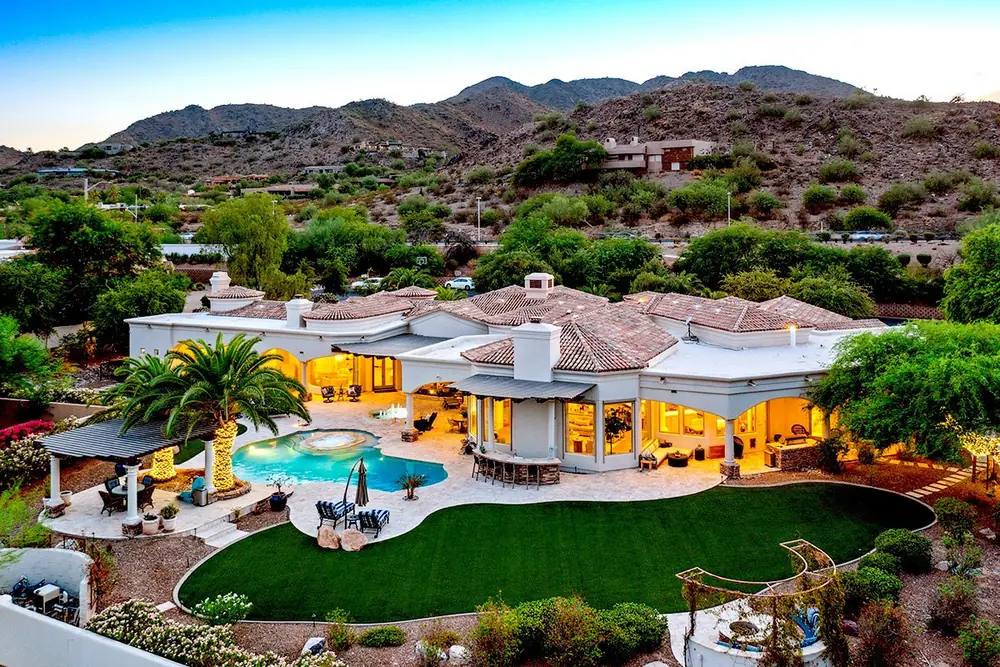 5 communitiesThe FoothillsCustom homes and desert views in Scottsdale & Paradise ValleyExplore The Foothills
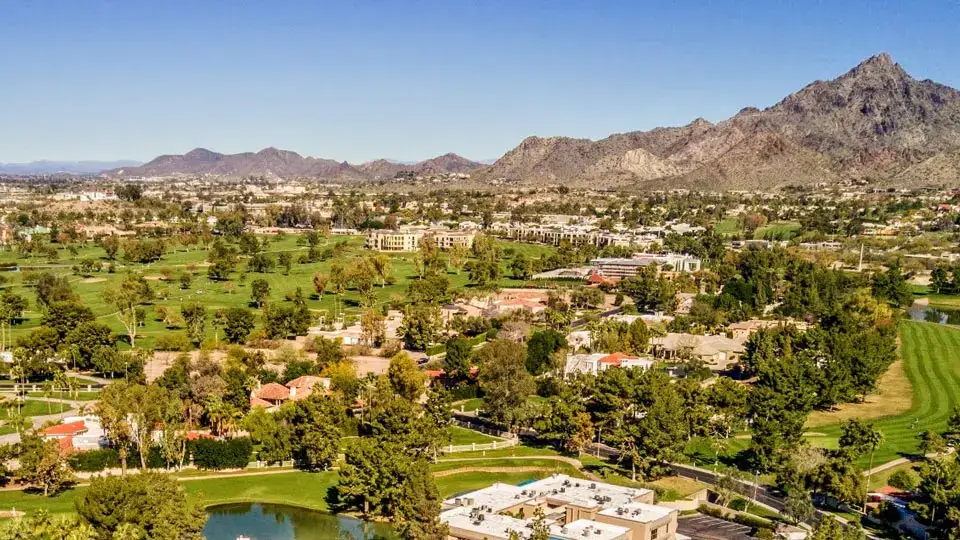 6 communitiesMetro PhoenixWalkable, in-town living in Downtown, Midtown & ArcadiaExplore Metro Phoenix
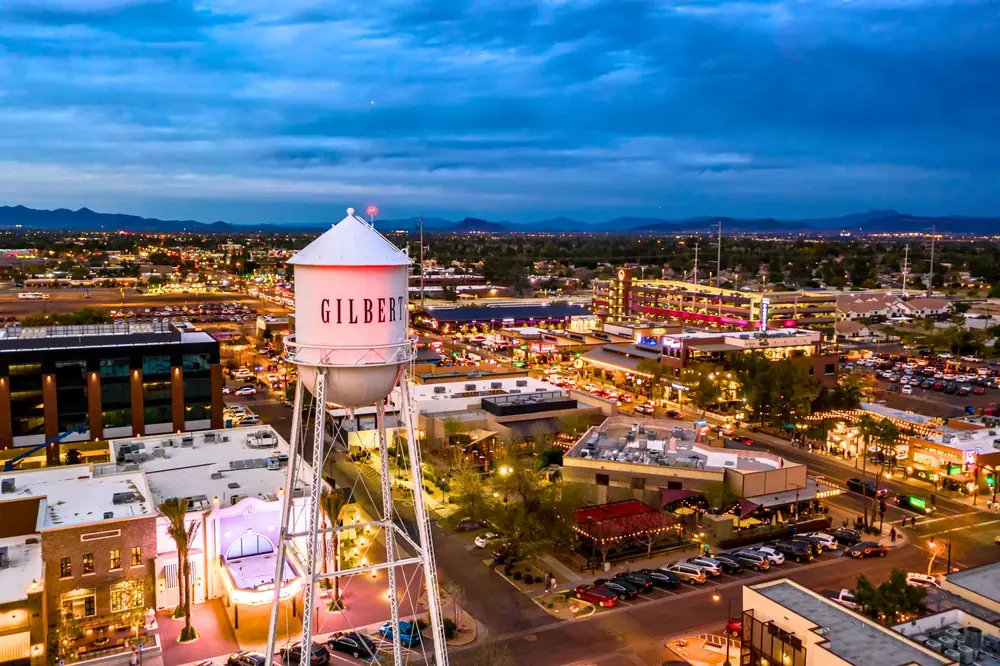 8 communitiesEast ValleyMaster-planned suburbs: Gilbert, Chandler, Mesa & Queen CreekExplore East Valley
Still deciding where to buy? Answer three quick questions and I’ll suggest two or three areas that fit. Get a free Area Match →
Slide to your monthly gross income for a rough estimate. This is a fast starting point — the detailed calculator below gets more specific.
Want a real number instead of an estimate? A pre-approval gives you one. Start My Home Search →
Buying without a large down payment is more common than you'd think. Here's the landscape of options — a lender partner can tell you exactly what you qualify for.
Conventional and FHA financing designed to get you in the door with less than a traditional down payment — popular with first-time buyers and buyers rebuilding credit.
State and local programs that can help cover some or all of your down payment and closing costs, often with no monthly payment required.
Government-backed options for eligible veterans, service members and buyers in eligible areas. A lender can tell you exactly what you’d need at closing.
Not sure which program fits your situation? I can connect you with a trusted lender who works these programs every day and can walk you through real numbers based on your credit and income.
A quick estimate — adjust the numbers to match your situation. This doesn't include taxes/insurance escrow variations, so treat it as a starting point, not a loan quote.
Tell me what you’re looking for and I’ll help you map out the next steps. No pressure, no obligation.
Closing costs typically run 2–5% of the purchase price and cover things like loan origination, title insurance, and appraisal fees. In many Arizona transactions, buyers and sellers each cover certain costs, and some can be negotiated as seller concessions.
Having your own agent means someone is working exclusively for your interests during negotiations, inspections, and closing. Before we tour homes together, we'll sign a short written buyer agreement that spells out what I'll do for you and how I'm paid. Agent compensation isn't set by law and is always negotiable, and in many transactions some or all of it is paid by the seller or builder, so I'll walk you through every option before we start.
Once you're under contract, most Arizona closings take 30–45 days. The house-hunting phase before that varies widely — some buyers find "the one" in a weekend, others take a few months.
Contingencies are conditions that must be met before your purchase becomes final — most commonly financing, appraisal, and inspection contingencies. They protect your earnest money by giving you a legal way to cancel and get it back if something doesn't check out, rather than being locked into the deal no matter what.
Earnest money is a deposit — typically 1–3% of the purchase price — that shows the seller you're serious. It's held by a neutral escrow company, not the seller. If you cancel within your contingency periods, it's refundable. If you cancel outside those windows without a valid contingency, it's usually not.
If the appraised value comes in below the purchase price, you generally have three options: renegotiate the price with the seller, cover the difference in cash, or cancel the contract under an appraisal contingency and get your earnest money back. Which option makes sense depends on the specific gap and how competitive the market is.
A properly written financing contingency protects you here: if you're denied a loan despite a good-faith effort to secure one, you can cancel the contract and recover your earnest money. This is why getting a strong pre-approval upfront — not just a quick pre-qualification — matters so much.
With new construction, you're often working with the builder's own sales representative, who represents the builder's interests, not yours — bringing your own agent often costs you nothing extra, since many builders pay the buyer's agent (I'll confirm with the builder up front), and it ensures someone is negotiating on your behalf. Builder contracts, timelines, and upgrade options also work differently than a typical resale transaction, so it's worth understanding before you sign anything at the model home.